Our parents spent years protecting us. We should have the right to protect them, too.
The Issue
When we are young, our parents carry us on their health insurance. They take us to doctors, fill our prescriptions, sit beside us when we’re sick, and do everything within their power to make sure money never determines whether we receive the medical care we need.
Today, federal law allows parents to keep their children on their health insurance plans until age 26.
But what happens when those roles reverse?
What happens when our parents grow older and we become the ones who want to protect them?
I am asking lawmakers, policymakers, employers, and health insurance regulators to create a pathway that allows working adults to add their aging parents to employer-sponsored health insurance plans beginning at age 65, without requiring those parents to live in our homes, be disabled, be financially dependent upon us, or require us to be their full-time caregivers.
For parents who are enrolled in Medicare, employer-sponsored coverage should be permitted to coordinate with Medicare according to applicable federal rules so families have another option for managing the medical expenses Medicare does not fully cover.
Independence should not disqualify our parents from receiving our help.
An aging parent can be perfectly capable of living independently and still struggle tremendously with the cost of healthcare.
Those are two completely different things.
Our parents should not have to surrender their independence, move into our homes, or become legally or financially dependent upon us before we are allowed to help provide them with better health coverage.
Being able to live independently does not mean someone can afford thousands of dollars in medical expenses.
I see this reality in my own family.
My father spends thousands of dollars on healthcare. He has reached a point where he sometimes has to decide which parts of his health he can afford to address.
He has been prescribed a medication for his prostate that he is expected to take long-term, but the cost has caused him to go without it.
His diabetes-related expenses have also become overwhelming. His costs associated with his Dexcom supplies have reached hundreds of dollars per month, and the cost of Ozempic has also made it difficult for him to consistently afford a medication he needs.
As his daughter, knowing that my father is making medical decisions based not on what his doctor believes is best for him, but on what he can afford, is heartbreaking.
And he is far from the only parent facing this reality.
My in-laws are retired and have Medicare, yet they still face medical costs that are significant compared with their retirement income. Sometimes they hesitate to go to the doctor when they don’t feel well because they are afraid of the bill that may come afterward.
Think about that.
People who spent decades working, raising families, paying taxes, contributing to their communities, and caring for everyone around them can reach retirement and become afraid to seek medical attention because getting sick might cost more than they can afford.
That is not what healthcare security should look like.
We aren’t asking for free healthcare.
We are asking for the opportunity to help pay for our parents’ healthcare through insurance benefits available to us as working adults.
We are willing to pay the additional premiums required to add them.
We are willing to take responsibility for that additional coverage.
We simply want the option.
If an employer-sponsored plan can offer family coverage for a spouse and children, families should be allowed to purchase coverage for an aging parent as well.
And Medicare eligibility should not automatically close that door. Where Medicare remains primary, employer-sponsored coverage could operate alongside it according to federal coordination-of-benefits rules.
This is not about taking Medicare away.
It is about giving families another layer of protection.
Our parents should not have to become helpless before we are allowed to help them.
This may be the most important part.
I do not want to wait until my father is unable to care for himself before the system recognizes that I should be allowed to help care for him.
I don’t want our parents to have to become seriously ill, disabled, impoverished, or dependent before their adult children are given meaningful options to help them.
Preventative care should come before crisis.
We should be able to help our parents afford medications before skipping those medications damages their health.
We should be able to help them afford doctor’s appointments before avoiding an appointment turns a manageable problem into an emergency.
We should be able to protect them while they are still independent.
They carried us. Let us carry them when they need us.
For the first years of our lives, our parents were responsible for protecting us.
Eventually, many of us reach an age where we find ourselves looking back at the people who raised us and realizing that they need us now.
Maybe they don’t need us to cook their meals.
Maybe they don’t need us to manage their finances.
Maybe they don’t need to live in our homes.
Maybe they don’t need a caregiver at all.
Maybe they just need a little help.
And if their adult children have access to health insurance and are willing to pay to extend that protection to them, the law should not unnecessarily stand in the way.
We are calling for change.
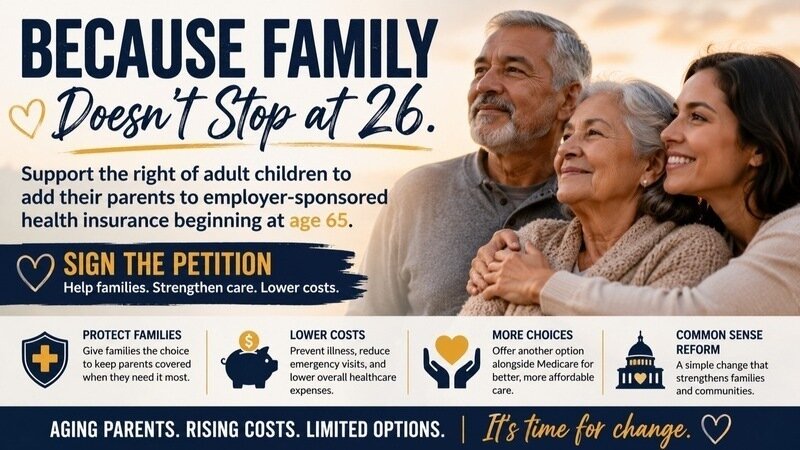
We call upon Congress and appropriate federal agencies to establish protections that allow adult children to enroll eligible aging parents in employer-sponsored health plans, beginning at age 65, regardless of whether the parent lives with the adult child or qualifies as the adult child’s tax dependent.
We ask that any new policy:
Allow employees to add a parent, stepparent, or adoptive parent beginning at age 65.
Not require the parent to live in the employee’s household.
Not require the employee to be the parent’s legal caregiver.
Not require the parent to surrender their independence or prove disability simply to qualify.
Allow Medicare and employer-sponsored insurance to coordinate benefits under appropriate federal rules when the parent is Medicare-eligible.
Permit employers and insurers to charge an appropriate additional family premium for the parent’s coverage rather than forcing employers to absorb the entire cost.
Protect participating families from unreasonable restrictions that make the benefit practically impossible to use.
This would not force every adult child to cover a parent.
It would not force every parent to enroll.
It would simply give American families a choice that many of us desperately wish we had.
Please sign this petition.
Sign if you have ever watched a parent or grandparent worry about the cost of a prescription.
Sign if someone you love has postponed a doctor’s appointment because they were afraid of the bill.
Sign if you have ever wished you could put your parents on your insurance and been frustrated to discover how difficult or impossible that can be.
Sign even if your parents don’t need this today, because one day they might.
And someday, we will be the aging parents.
Our children should not have to watch us choose between our health and our bank accounts either.
Our parents spent decades protecting us.
Give us the right to protect them back.

26
The Issue
When we are young, our parents carry us on their health insurance. They take us to doctors, fill our prescriptions, sit beside us when we’re sick, and do everything within their power to make sure money never determines whether we receive the medical care we need.
Today, federal law allows parents to keep their children on their health insurance plans until age 26.
But what happens when those roles reverse?
What happens when our parents grow older and we become the ones who want to protect them?
I am asking lawmakers, policymakers, employers, and health insurance regulators to create a pathway that allows working adults to add their aging parents to employer-sponsored health insurance plans beginning at age 65, without requiring those parents to live in our homes, be disabled, be financially dependent upon us, or require us to be their full-time caregivers.
For parents who are enrolled in Medicare, employer-sponsored coverage should be permitted to coordinate with Medicare according to applicable federal rules so families have another option for managing the medical expenses Medicare does not fully cover.
Independence should not disqualify our parents from receiving our help.
An aging parent can be perfectly capable of living independently and still struggle tremendously with the cost of healthcare.
Those are two completely different things.
Our parents should not have to surrender their independence, move into our homes, or become legally or financially dependent upon us before we are allowed to help provide them with better health coverage.
Being able to live independently does not mean someone can afford thousands of dollars in medical expenses.
I see this reality in my own family.
My father spends thousands of dollars on healthcare. He has reached a point where he sometimes has to decide which parts of his health he can afford to address.
He has been prescribed a medication for his prostate that he is expected to take long-term, but the cost has caused him to go without it.
His diabetes-related expenses have also become overwhelming. His costs associated with his Dexcom supplies have reached hundreds of dollars per month, and the cost of Ozempic has also made it difficult for him to consistently afford a medication he needs.
As his daughter, knowing that my father is making medical decisions based not on what his doctor believes is best for him, but on what he can afford, is heartbreaking.
And he is far from the only parent facing this reality.
My in-laws are retired and have Medicare, yet they still face medical costs that are significant compared with their retirement income. Sometimes they hesitate to go to the doctor when they don’t feel well because they are afraid of the bill that may come afterward.
Think about that.
People who spent decades working, raising families, paying taxes, contributing to their communities, and caring for everyone around them can reach retirement and become afraid to seek medical attention because getting sick might cost more than they can afford.
That is not what healthcare security should look like.
We aren’t asking for free healthcare.
We are asking for the opportunity to help pay for our parents’ healthcare through insurance benefits available to us as working adults.
We are willing to pay the additional premiums required to add them.
We are willing to take responsibility for that additional coverage.
We simply want the option.
If an employer-sponsored plan can offer family coverage for a spouse and children, families should be allowed to purchase coverage for an aging parent as well.
And Medicare eligibility should not automatically close that door. Where Medicare remains primary, employer-sponsored coverage could operate alongside it according to federal coordination-of-benefits rules.
This is not about taking Medicare away.
It is about giving families another layer of protection.
Our parents should not have to become helpless before we are allowed to help them.
This may be the most important part.
I do not want to wait until my father is unable to care for himself before the system recognizes that I should be allowed to help care for him.
I don’t want our parents to have to become seriously ill, disabled, impoverished, or dependent before their adult children are given meaningful options to help them.
Preventative care should come before crisis.
We should be able to help our parents afford medications before skipping those medications damages their health.
We should be able to help them afford doctor’s appointments before avoiding an appointment turns a manageable problem into an emergency.
We should be able to protect them while they are still independent.
They carried us. Let us carry them when they need us.
For the first years of our lives, our parents were responsible for protecting us.
Eventually, many of us reach an age where we find ourselves looking back at the people who raised us and realizing that they need us now.
Maybe they don’t need us to cook their meals.
Maybe they don’t need us to manage their finances.
Maybe they don’t need to live in our homes.
Maybe they don’t need a caregiver at all.
Maybe they just need a little help.
And if their adult children have access to health insurance and are willing to pay to extend that protection to them, the law should not unnecessarily stand in the way.
We are calling for change.
We call upon Congress and appropriate federal agencies to establish protections that allow adult children to enroll eligible aging parents in employer-sponsored health plans, beginning at age 65, regardless of whether the parent lives with the adult child or qualifies as the adult child’s tax dependent.
We ask that any new policy:
Allow employees to add a parent, stepparent, or adoptive parent beginning at age 65.
Not require the parent to live in the employee’s household.
Not require the employee to be the parent’s legal caregiver.
Not require the parent to surrender their independence or prove disability simply to qualify.
Allow Medicare and employer-sponsored insurance to coordinate benefits under appropriate federal rules when the parent is Medicare-eligible.
Permit employers and insurers to charge an appropriate additional family premium for the parent’s coverage rather than forcing employers to absorb the entire cost.
Protect participating families from unreasonable restrictions that make the benefit practically impossible to use.
This would not force every adult child to cover a parent.
It would not force every parent to enroll.
It would simply give American families a choice that many of us desperately wish we had.
Please sign this petition.
Sign if you have ever watched a parent or grandparent worry about the cost of a prescription.
Sign if someone you love has postponed a doctor’s appointment because they were afraid of the bill.
Sign if you have ever wished you could put your parents on your insurance and been frustrated to discover how difficult or impossible that can be.
Sign even if your parents don’t need this today, because one day they might.
And someday, we will be the aging parents.
Our children should not have to watch us choose between our health and our bank accounts either.
Our parents spent decades protecting us.
Give us the right to protect them back.
The Decision Makers


Petition Updates
Share this petition
Petition created on February 15, 2026