Freeze foreclosures- sheriff sales and evictions on owner-occupied primary homes
The Issue
SERVICERS CAUSED THE 2008 CRASH. NOW THEY ARE DOING IT AGAIN, BUT THEY ARE BIGGER, MORE ORGANIZED, AND THEIR TARGET IS THE VULNERABLE HOMEOWNER.
In 2012 there was a payment of $25 billion, and the servicers, instead of really helping people, made more money. Now they are collecting on those mortgages and displacing hundreds of thousands using forged paperwork. Some foreclosures are legitimate. Most of them are manufactured, and many are deed theft. Attorneys are being impersonated by bad actors. Homeowners are not being served and have no chance to defend the foreclosure until the sheriff comes to take them out of the house. Some questionable law firms have gone as far as using family members to forge documents from vulnerable homeowners and get them signed by clerks without judge review. Companies that offer foreclosure help may be accelerating the foreclosure, posing as attorneys when they are not.
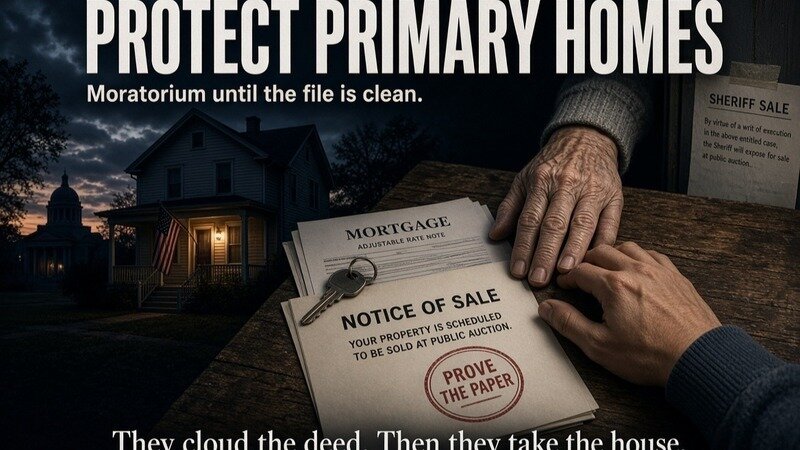
Freeze sheriff sales and trustee sales on owner-occupied primary homes until the file is clean.
They manipulate the file.
They manufacture hardship.
They stall or kill the refinance.
They cloud the deed so no honest lender will touch it.
Then they call it default while you are current and take the house.
That is not following the rules established after 2008. That is a trap.
If the deed is clouded, foreclosure is not a remedy. It is the payoff. If they blocked the refinance, they do not get to profit from the default they helped create. If they keep asking for the same papers while a sale date is set, that is dual-tracking.
Due process: serve the owner, open the file, test the paper.
Unjust enrichment: they do not keep the payments, the junk fees, and the equity.
Predatory collection: no manufactured default, no fake lien, no judgment bigger than the lawful debt.
Moratorium on primary homes until:
Title is unclouded or a court has ruled on the cloud.
Refinance or sale by the owner is not being blocked by a defective lien or assignment.
Hardship/mod review is finished in writing — no sale during “we need those documents again.”
Note, assignment chain, payment history, and proof of service are in the file.
Every payment is credited and the balance is not inflated.
President, Congress, governors, CFPB, FHFA: homelessness prevention is a clean deed and a paused sale — not a shelter bed after the lock changes.
PROTECT THE ELDERS. PROTECT THE VULNERABLE. PROTECT THE AMERICAN DREAM.
31
The Issue
SERVICERS CAUSED THE 2008 CRASH. NOW THEY ARE DOING IT AGAIN, BUT THEY ARE BIGGER, MORE ORGANIZED, AND THEIR TARGET IS THE VULNERABLE HOMEOWNER.
In 2012 there was a payment of $25 billion, and the servicers, instead of really helping people, made more money. Now they are collecting on those mortgages and displacing hundreds of thousands using forged paperwork. Some foreclosures are legitimate. Most of them are manufactured, and many are deed theft. Attorneys are being impersonated by bad actors. Homeowners are not being served and have no chance to defend the foreclosure until the sheriff comes to take them out of the house. Some questionable law firms have gone as far as using family members to forge documents from vulnerable homeowners and get them signed by clerks without judge review. Companies that offer foreclosure help may be accelerating the foreclosure, posing as attorneys when they are not.
Freeze sheriff sales and trustee sales on owner-occupied primary homes until the file is clean.
They manipulate the file.
They manufacture hardship.
They stall or kill the refinance.
They cloud the deed so no honest lender will touch it.
Then they call it default while you are current and take the house.
That is not following the rules established after 2008. That is a trap.
If the deed is clouded, foreclosure is not a remedy. It is the payoff. If they blocked the refinance, they do not get to profit from the default they helped create. If they keep asking for the same papers while a sale date is set, that is dual-tracking.
Due process: serve the owner, open the file, test the paper.
Unjust enrichment: they do not keep the payments, the junk fees, and the equity.
Predatory collection: no manufactured default, no fake lien, no judgment bigger than the lawful debt.
Moratorium on primary homes until:
Title is unclouded or a court has ruled on the cloud.
Refinance or sale by the owner is not being blocked by a defective lien or assignment.
Hardship/mod review is finished in writing — no sale during “we need those documents again.”
Note, assignment chain, payment history, and proof of service are in the file.
Every payment is credited and the balance is not inflated.
President, Congress, governors, CFPB, FHFA: homelessness prevention is a clean deed and a paused sale — not a shelter bed after the lock changes.
PROTECT THE ELDERS. PROTECT THE VULNERABLE. PROTECT THE AMERICAN DREAM.
Supporter Voices
Petition Updates
Share this petition
Petition created on September 20, 2026