9 Ways Texas Protects Insurance Companies Instead of You. Sign to Change It.
The Issue
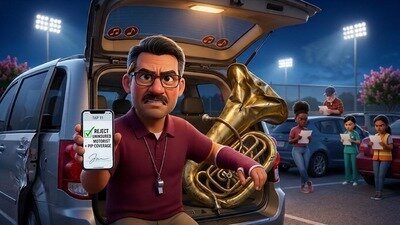
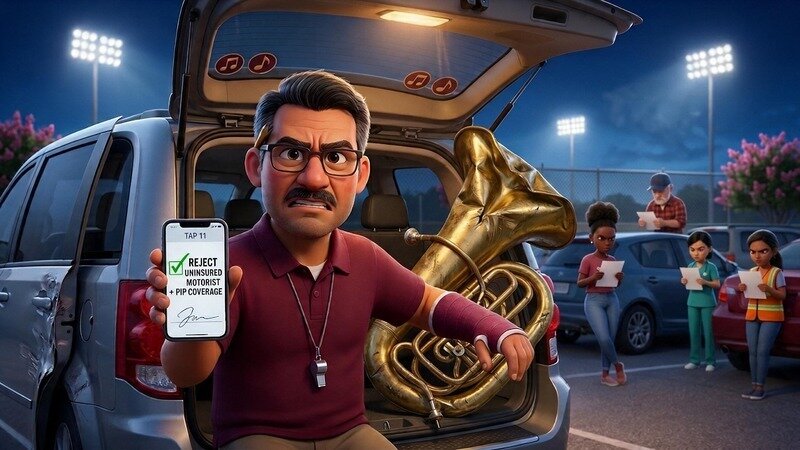
Rafa did everything right. He is a high school band director in Southwest Houston. When the school district cut the band budget, he started counting every dollar, so he walked into a First Acceptance (allegedly) storefront to save eleven dollars a month. The agent's thumbs moved fast: tap here, here, here. Fourteen taps in ninety seconds. One screen she never read out loud: "I reject uninsured motorist and personal injury protection coverage." Then, on a Friday night after the football game, a pickup ran a red light on Westheimer. Rafa's right wrist broke. His son Diego's tuba folded like a paper cup. The other driver's insurance had lapsed. Rafa's claim? Denied. Refund of eleven months of premiums? Not without proof of fraud. Offer? Four thousand dollars, when his medical bills alone were eleven thousand. That company was First Acceptance. Allegedly.
Rafa isn't real. These Texas laws are VERY real. The 9 barriers he hit are real Texas law. Here is what any Texas driver faces when an insurance company lets them down:
- A tap is your signature. In Texas, an electronic signature is yours if it was your act. Fourteen taps, all yours.
- If you had the chance to read it, the Texas Supreme Court says the law presumes you know it and accept it. Ninety seconds was the chance. Since 2015.
- Uninsured motorist coverage and personal injury protection don't apply if you rejected them in writing. Tap eleven. Gone.
- Money you pay knowing the facts can't be recovered unless there's fraud, deception, duress or compulsion. Proving that is your job. Texas Supreme Court, 2005.
- Keep the benefits after you know the facts, and you may have approved the deal. The word is "ratified." Texas Supreme Court, 1980.
- Before you can sue under the insurance code, you have to send written notice at least 61 days ahead. Two more months of waiting, on their schedule.
- The whole insurance-code claim has two years from when it happened, or when you found out.
- Punishment money is capped: two times your money losses, plus pain-and-suffering money up to $750,000, or $200,000, whichever is more. A company can do the math first.
- Turn down their offer, and if the final judgment is a lot less than that offer, Texas makes you pay their litigation costs. The offer isn't a gift. It's a dare.
Most of these were written, or rewritten, under Gov. Rick Perry. The settlement penalty came in House Bill 4, by Rep. Joe Nixon. The punishment cap started in 1987 under Gov. Bill Clements, was rewritten in 1995 under Gov. George W. Bush, and again in 2003. Every legislature since has left all nine standing.
The one thing Texas got right: you can sue your insurance company yourself for unfair or deceptive practices, and if the jury finds they did it knowingly, it can award up to three times your actual damages. One out of ten.
WE ASK GOV. ABBOTT, AG PAXTON, COMMISSIONER CRAWFORD AND THE TEXAS LEGISLATURE TO:
- Require insurers to explain uninsured motorist and personal injury protection coverage in plain words, out loud, before any tap counts as rejecting it.
- Require a real copy of every policy and every rejection form in the driver's hands before a tap counts as a signature.
- Stop treating ninety seconds on a tablet as "the chance to read it."
- Let drivers get back premiums paid for coverage they never knowingly gave up.
- Stop counting a renewal or a kept policy as approval when the driver is still fighting the claim.
- Stop the 61-day notice and the two-year clock from running against drivers while an insurer stalls.
- Lift the punishment cap and end the settlement-offer trap when a company profits from deceiving its customers.
This isn't one bad agent. It's a system that makes fighting back too expensive for working people. Texas drivers are required by law to buy insurance. Texas law should protect them when that insurance leaves them exposed.
We are watching how you vote.
1
The Issue
Rafa did everything right. He is a high school band director in Southwest Houston. When the school district cut the band budget, he started counting every dollar, so he walked into a First Acceptance (allegedly) storefront to save eleven dollars a month. The agent's thumbs moved fast: tap here, here, here. Fourteen taps in ninety seconds. One screen she never read out loud: "I reject uninsured motorist and personal injury protection coverage." Then, on a Friday night after the football game, a pickup ran a red light on Westheimer. Rafa's right wrist broke. His son Diego's tuba folded like a paper cup. The other driver's insurance had lapsed. Rafa's claim? Denied. Refund of eleven months of premiums? Not without proof of fraud. Offer? Four thousand dollars, when his medical bills alone were eleven thousand. That company was First Acceptance. Allegedly.
Rafa isn't real. These Texas laws are VERY real. The 9 barriers he hit are real Texas law. Here is what any Texas driver faces when an insurance company lets them down:
- A tap is your signature. In Texas, an electronic signature is yours if it was your act. Fourteen taps, all yours.
- If you had the chance to read it, the Texas Supreme Court says the law presumes you know it and accept it. Ninety seconds was the chance. Since 2015.
- Uninsured motorist coverage and personal injury protection don't apply if you rejected them in writing. Tap eleven. Gone.
- Money you pay knowing the facts can't be recovered unless there's fraud, deception, duress or compulsion. Proving that is your job. Texas Supreme Court, 2005.
- Keep the benefits after you know the facts, and you may have approved the deal. The word is "ratified." Texas Supreme Court, 1980.
- Before you can sue under the insurance code, you have to send written notice at least 61 days ahead. Two more months of waiting, on their schedule.
- The whole insurance-code claim has two years from when it happened, or when you found out.
- Punishment money is capped: two times your money losses, plus pain-and-suffering money up to $750,000, or $200,000, whichever is more. A company can do the math first.
- Turn down their offer, and if the final judgment is a lot less than that offer, Texas makes you pay their litigation costs. The offer isn't a gift. It's a dare.
Most of these were written, or rewritten, under Gov. Rick Perry. The settlement penalty came in House Bill 4, by Rep. Joe Nixon. The punishment cap started in 1987 under Gov. Bill Clements, was rewritten in 1995 under Gov. George W. Bush, and again in 2003. Every legislature since has left all nine standing.
The one thing Texas got right: you can sue your insurance company yourself for unfair or deceptive practices, and if the jury finds they did it knowingly, it can award up to three times your actual damages. One out of ten.
WE ASK GOV. ABBOTT, AG PAXTON, COMMISSIONER CRAWFORD AND THE TEXAS LEGISLATURE TO:
- Require insurers to explain uninsured motorist and personal injury protection coverage in plain words, out loud, before any tap counts as rejecting it.
- Require a real copy of every policy and every rejection form in the driver's hands before a tap counts as a signature.
- Stop treating ninety seconds on a tablet as "the chance to read it."
- Let drivers get back premiums paid for coverage they never knowingly gave up.
- Stop counting a renewal or a kept policy as approval when the driver is still fighting the claim.
- Stop the 61-day notice and the two-year clock from running against drivers while an insurer stalls.
- Lift the punishment cap and end the settlement-offer trap when a company profits from deceiving its customers.
This isn't one bad agent. It's a system that makes fighting back too expensive for working people. Texas drivers are required by law to buy insurance. Texas law should protect them when that insurance leaves them exposed.
We are watching how you vote.
Petition Updates
Share this petition
Petition created on October 21, 2026