18 Ways Georgia Protects Insurance Companies Instead of You. Sign to Change It.
The Issue
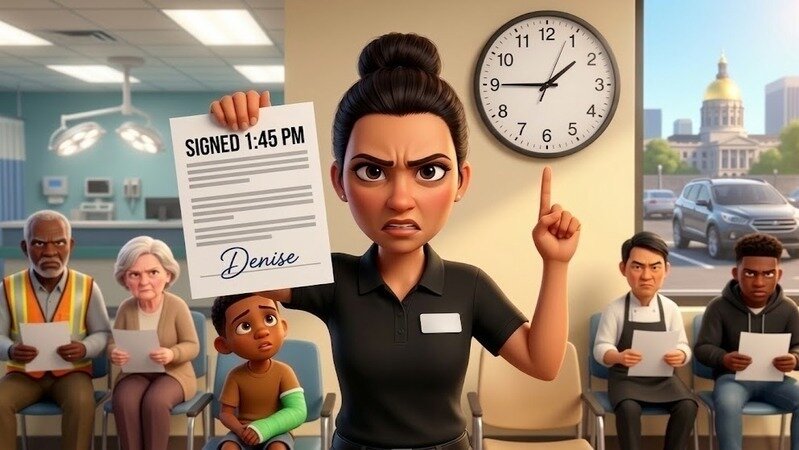
Denise did everything right. She asked for full coverage because her lender required it. She paid her down payment. Then, while she spent four hours in the ER with her son and his broken arm, "her" signature showed up on a policy she never saw: liability only, no collision, and a written "rejection" of her uninsured motorist coverage. The signing link never went to her. It went to the agent's inbox. That company was First Acceptance. Allegedly.
Denise is a character in our story. The 18 barriers she hit are real Georgia law. Here is what any Georgia driver faces when an insurance company cheats them:
- A signature only counts if it was "the act of the person," but YOU have to prove it wasn't yours.
- Electronic delivery requires your consent, but nobody enforces it. "It's in your email, ma'am."
- Every payment you made can be called "voluntary," and voluntary payments don't come back.
- Uninsured motorist coverage can only be rejected in writing, so a forged rejection wipes it out.
- Even with that coverage, you must sue the uninsured driver and win first.
- You can't go straight to the other driver's insurer without a court judgment.
- If they act in bad faith, the penalty is capped: half the loss or $5,000. For a company that took in $112 million in Georgia in one year, that's about 23 minutes of premiums.
- Georgia's unfair-claims law says you can't sue under it. Only the state can act.
- The Insurance Commissioner "may" act on your complaint. May. Not must.
- When the agent is fired, the report goes to the state, not to you.
- "One who can read must read," even when nobody ever gave you the papers.
- Keep the policy because you need your car for work? They call that agreeing to it.
- In product cases, Georgia takes 75% of the punishment money.
- Senate Bill 68 can freeze your case while the company asks the judge to throw it out.
- Turn down a lowball offer and win less later? You pay THEIR lawyers.
- Punishment for the company is capped at $250,000.
- When they meant to do it, only the individual agent pays more. Not the company that cashed your checks.
- The "discount" on your bill can be the clause that takes away a jury's power to punish them.
The one thing Georgia got right: insurers can't force you into private arbitration. One out of nineteen.
WE ASK GOV. KEMP, COMMISSIONER KING AND THE GENERAL ASSEMBLY TO:
- Put the burden of proof on the company when a customer says "that's not my signature."
- Enforce electronic-delivery consent and require a real copy of every policy in the driver's hands.
- Require the Commissioner to investigate every forged-signature complaint. "Must," not "may."
- Give drivers the right to sue under the unfair-claims law.
- Raise the bad-faith penalty so it actually stops bad behavior.
- End the discovery freeze and the settlement-offer trap for everyday drivers.
- Lift the punishment cap when a company profits from fraud.
This isn't one bad agent. It's a system that makes fighting back too expensive for working people. Georgia drivers are required by law to buy insurance. Georgia law should protect them when that insurance is a lie.
We are watching how you vote.
1
The Issue
Denise did everything right. She asked for full coverage because her lender required it. She paid her down payment. Then, while she spent four hours in the ER with her son and his broken arm, "her" signature showed up on a policy she never saw: liability only, no collision, and a written "rejection" of her uninsured motorist coverage. The signing link never went to her. It went to the agent's inbox. That company was First Acceptance. Allegedly.
Denise is a character in our story. The 18 barriers she hit are real Georgia law. Here is what any Georgia driver faces when an insurance company cheats them:
- A signature only counts if it was "the act of the person," but YOU have to prove it wasn't yours.
- Electronic delivery requires your consent, but nobody enforces it. "It's in your email, ma'am."
- Every payment you made can be called "voluntary," and voluntary payments don't come back.
- Uninsured motorist coverage can only be rejected in writing, so a forged rejection wipes it out.
- Even with that coverage, you must sue the uninsured driver and win first.
- You can't go straight to the other driver's insurer without a court judgment.
- If they act in bad faith, the penalty is capped: half the loss or $5,000. For a company that took in $112 million in Georgia in one year, that's about 23 minutes of premiums.
- Georgia's unfair-claims law says you can't sue under it. Only the state can act.
- The Insurance Commissioner "may" act on your complaint. May. Not must.
- When the agent is fired, the report goes to the state, not to you.
- "One who can read must read," even when nobody ever gave you the papers.
- Keep the policy because you need your car for work? They call that agreeing to it.
- In product cases, Georgia takes 75% of the punishment money.
- Senate Bill 68 can freeze your case while the company asks the judge to throw it out.
- Turn down a lowball offer and win less later? You pay THEIR lawyers.
- Punishment for the company is capped at $250,000.
- When they meant to do it, only the individual agent pays more. Not the company that cashed your checks.
- The "discount" on your bill can be the clause that takes away a jury's power to punish them.
The one thing Georgia got right: insurers can't force you into private arbitration. One out of nineteen.
WE ASK GOV. KEMP, COMMISSIONER KING AND THE GENERAL ASSEMBLY TO:
- Put the burden of proof on the company when a customer says "that's not my signature."
- Enforce electronic-delivery consent and require a real copy of every policy in the driver's hands.
- Require the Commissioner to investigate every forged-signature complaint. "Must," not "may."
- Give drivers the right to sue under the unfair-claims law.
- Raise the bad-faith penalty so it actually stops bad behavior.
- End the discovery freeze and the settlement-offer trap for everyday drivers.
- Lift the punishment cap when a company profits from fraud.
This isn't one bad agent. It's a system that makes fighting back too expensive for working people. Georgia drivers are required by law to buy insurance. Georgia law should protect them when that insurance is a lie.
We are watching how you vote.
Petition Updates
Share this petition
Petition created on October 15, 2026