11 Ways Tennessee Protects Insurance Companies Instead of You. Sign to Change It.
The Issue
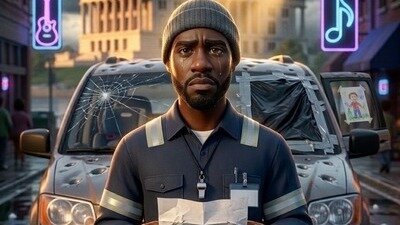
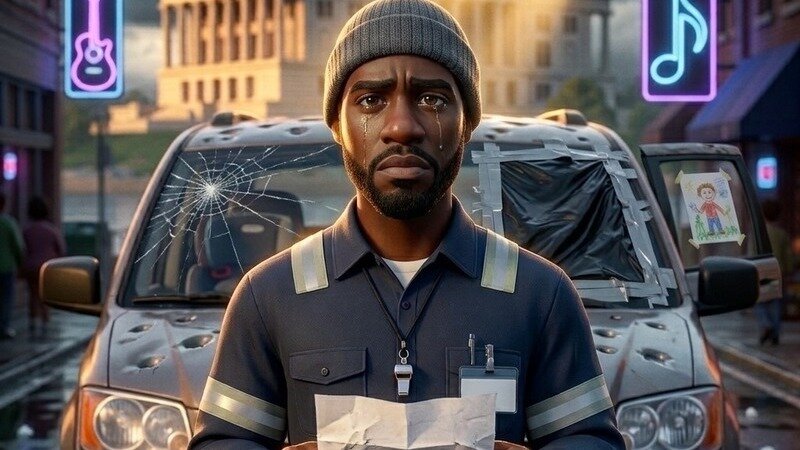
Darnell Hughes is 38 and lives in Memphis. He loads packages at an air-freight hub all night and raises twin girls on $688 a week. His 2014 minivan, Big Linda, is how he gets to work. He bought cheap full coverage at a strip-mall storefront for $96 a month. The papers were supposed to come by email. They never did. The next afternoon, while he slept, someone electronically signed a form rejecting his comprehensive coverage. His badge log shows he was home. The $96 kept leaving his account every month. Then hail wrecked the van, and the claim was denied because "he" rejected the coverage. The agent vanished. The company said he was on his own. The company was First Acceptance. Allegedly.
Darnell isn't real. These Tennessee laws are VERY real. The 11 barriers he hit are real Tennessee law. Here is what any Tennessee driver faces when an insurance company cheats them:
- An e-signature counts as "the act of the person," so the fight becomes who clicked, and you have to prove it wasn't you.
- Money you pay on your own is treated as voluntary. You don't get it back unless you prove fraud, accident, or mistake.
- Tennessee is not a "direct action" state. You can't sue the other driver's insurance company. You can only sue the driver.
- Before the company can be penalized for bad faith, you send a formal demand and wait 60 days. Sixty days without a van.
- Even then, the bad-faith penalty is capped at 25 percent, and you still have to prove bad faith.
- Since 2011, the insurance code is the "sole and exclusive" remedy. The Consumer Protection Act does not apply to insurance.
- The company pays punitive damages for its agent's act only in narrow cases, like when it approved the act knowing the harm. Proving what it knew is on you.
- Courts say you have a "duty to read" what you sign, even when you never got the papers and never signed.
- "You kept paying, so you approved it." Ratification takes full knowledge of the facts, but the burden of proving you didn't know lands on you.
- Arbitration clauses are "valid, enforceable, and irrevocable." A clause in a policy you never received can still send you to a private arbitrator, unless you first prove forgery.
- If your case is dismissed early, you pay the other side's costs and attorney's fees, up to $10,000. For Darnell, that is fourteen weeks of pay.
This isn't one bad agent. It's a system that makes fighting back too expensive for working people.
WE ASK GOV. LEE, COMMISSIONER LAWRENCE AND THE TENNESSEE GENERAL ASSEMBLY TO:
- Put the burden of proof on the company when a customer says "that's not my signature."
- Require insurers to put a real copy of every policy in the customer's hands, and to prove delivery.
- Stop calling payments for coverage you never got "voluntary." Make companies refund them when a signature is disputed.
- Shorten the 60-day wait and raise the 25 percent cap so bad faith actually costs something.
- Restore the Consumer Protection Act for insurance customers, or give drivers a real right to sue.
- Make the company answer for what its agents do in its name.
- Protect everyday drivers from the loser-pays rule and from forced arbitration in policies they never saw.
Sign this petition, then call your lawmakers: every Tennessee lawmaker's number is free at the link in bio (https://linktr.ee/thepeoplehavespoken1
We are watching how you vote.
1
The Issue
Darnell Hughes is 38 and lives in Memphis. He loads packages at an air-freight hub all night and raises twin girls on $688 a week. His 2014 minivan, Big Linda, is how he gets to work. He bought cheap full coverage at a strip-mall storefront for $96 a month. The papers were supposed to come by email. They never did. The next afternoon, while he slept, someone electronically signed a form rejecting his comprehensive coverage. His badge log shows he was home. The $96 kept leaving his account every month. Then hail wrecked the van, and the claim was denied because "he" rejected the coverage. The agent vanished. The company said he was on his own. The company was First Acceptance. Allegedly.
Darnell isn't real. These Tennessee laws are VERY real. The 11 barriers he hit are real Tennessee law. Here is what any Tennessee driver faces when an insurance company cheats them:
- An e-signature counts as "the act of the person," so the fight becomes who clicked, and you have to prove it wasn't you.
- Money you pay on your own is treated as voluntary. You don't get it back unless you prove fraud, accident, or mistake.
- Tennessee is not a "direct action" state. You can't sue the other driver's insurance company. You can only sue the driver.
- Before the company can be penalized for bad faith, you send a formal demand and wait 60 days. Sixty days without a van.
- Even then, the bad-faith penalty is capped at 25 percent, and you still have to prove bad faith.
- Since 2011, the insurance code is the "sole and exclusive" remedy. The Consumer Protection Act does not apply to insurance.
- The company pays punitive damages for its agent's act only in narrow cases, like when it approved the act knowing the harm. Proving what it knew is on you.
- Courts say you have a "duty to read" what you sign, even when you never got the papers and never signed.
- "You kept paying, so you approved it." Ratification takes full knowledge of the facts, but the burden of proving you didn't know lands on you.
- Arbitration clauses are "valid, enforceable, and irrevocable." A clause in a policy you never received can still send you to a private arbitrator, unless you first prove forgery.
- If your case is dismissed early, you pay the other side's costs and attorney's fees, up to $10,000. For Darnell, that is fourteen weeks of pay.
This isn't one bad agent. It's a system that makes fighting back too expensive for working people.
WE ASK GOV. LEE, COMMISSIONER LAWRENCE AND THE TENNESSEE GENERAL ASSEMBLY TO:
- Put the burden of proof on the company when a customer says "that's not my signature."
- Require insurers to put a real copy of every policy in the customer's hands, and to prove delivery.
- Stop calling payments for coverage you never got "voluntary." Make companies refund them when a signature is disputed.
- Shorten the 60-day wait and raise the 25 percent cap so bad faith actually costs something.
- Restore the Consumer Protection Act for insurance customers, or give drivers a real right to sue.
- Make the company answer for what its agents do in its name.
- Protect everyday drivers from the loser-pays rule and from forced arbitration in policies they never saw.
Sign this petition, then call your lawmakers: every Tennessee lawmaker's number is free at the link in bio (https://linktr.ee/thepeoplehavespoken1
We are watching how you vote.
Petition Updates
Share this petition
Petition created on October 21, 2026